Judo Capital Holdings
(ASX:JDO)
By Anton Crabbe 14th July 2026
JDO is a small bank in a big pond that lends mostly to SME’s in Australia. At the time of writing, they had a market cap of $1.3bn, revenue of $467.7m (FY25), ROE of 5.35% (FY25), total assets of $14.9bn (FY25) and trade on a PE of 11.
Compare this to CBA which has a market cap of $282.3bn, revenue of $28.6bn (FY25), ROE or 13.3% (FY25), total assets of $1.3t (FY25) and trade on a PE of 27.
Based on this you can see the market and investors see JDO as a lower quality bank and is part of the reason when on the 25th of June 2026, JDO announced to the market they now expect FY26 profit before tax to be in the range of $163-169m down from $180-190m due to an increase in bad debts. Their share price fell from circa $1.50 to 88c on the day.
However, since their listing in 2021, JDO have managed to grow their loan book 3.5 times from $3.5bn to $12.5bn and increase revenue from $28.2m to $423m in FY25. They also, expect their loan book to be in the range of $14.6-14.7bn in FY26.
Table 1.
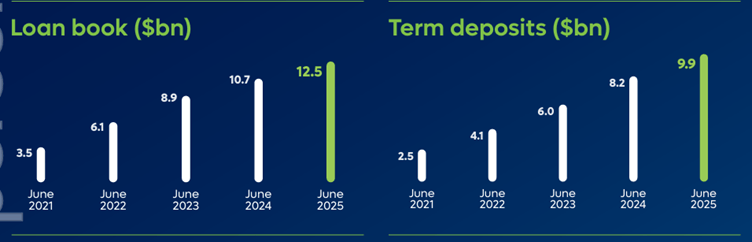
Source: JDO FY25 Annual Report
Table 2.
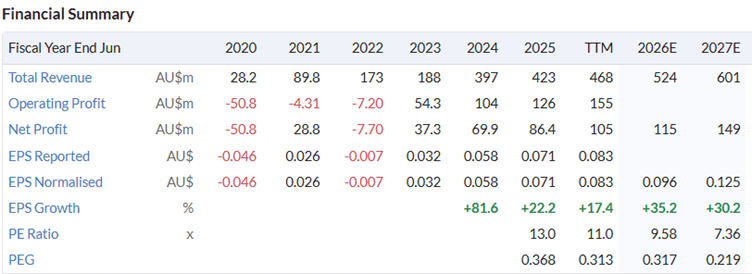
Source: Stockopeida
Furthermore, JDO can mix it with the major banks with some of their key metrics. In FY25 CBA had a CET1 of 12.3%, NIM 2.08%, and a CTI ratio of 45.7%. Table 3 shows that JDO had a superior NIM and CET1 in FY25 and in their market release on the 25th June 2026 JDO stated they expect their FY26 NIM to be 3.2%, CTI ratio to be below 48.5% and their CET1 to be ~12.4%. Which for a small growing bank in a competitive environment is impressive, especially when coupled with the growth in their loan book and revenues. JDO also reaffirmed their FY27 guidance of profit before tax to be between $210-220m.
The one ratio JDO does need to improve is their ROE. Basically, a bank is a ball of equity or cash that they leverage and then lend this money out at a greater margin than they borrowed it at. This is why the NIM and ROE are critical ratios for banks. As all they are is equity, and a ROE of 5.3% is not good enough for a bank. JDO would understand this and in their reporting, they do expect ROE to be in the mid to low teens at some point in the future. If they can keep growing close to or greater than their current rate. I think this is achievable as the more you leverage the greater your ROE will be, all things being equal. This would be one ratio I would be paying close attention to if I was a long-term investor in JDO. As a higher ROE is the only way they will create long-term value and grow their share price.
Table 3.
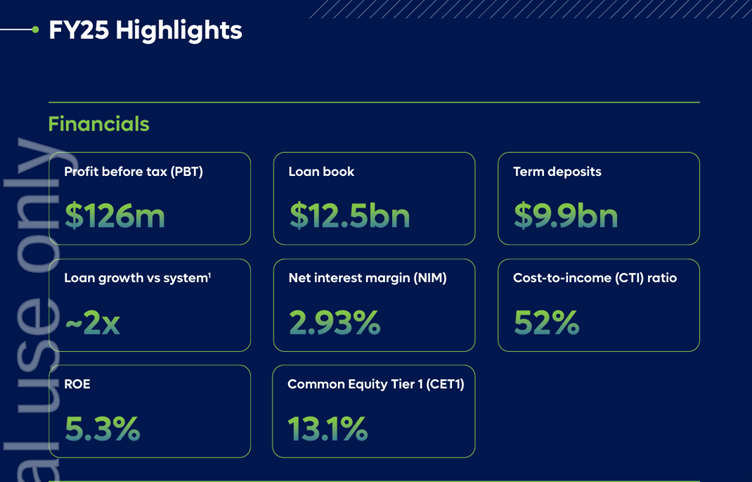
Source: JDO FY25 Annual Report
Based on the above, JDO are a quality growing bank that is obviously filling a gap in the market, and their loans are in demand by SME’s. But, drilling down a bit further into their June 25th announcement. JDO stated their 90+ Days Past Due and Impaired loans (90+ DPD) would increase from 2.65% to 3.0% in FY26. This has increased from 2.31% in FY24 and is one of the main reasons investors sold off their shares, as they are concerned about the quality of their loan book. But when you compare the increase in 90+ DPD and impaired loans to the growth in their loan book. I think an increase is only natural when a bank is growing like JDO, and JDO does expect 90+ DPD and impaired loans to stabilise in FY27.
JDO play a critical role in our economy by lending to SME’s. Access to capital for SME’s is crucial and is a major key to the success of small business. For the economy to grow and be strong in the long-term it needs a thriving small business sector. As Warren Buffet said, “You don’t bet against the US economy” and he made billions of this theory. My view is, for all of us to prosper we need the economy to be strong, and a major driver of the economy is small business. So, if JDO does well, we all will do well. Whether you like their share or not, we are aligned with their success.
Valuation:
I am keeping this simple. Based on a PE of 11 and their FY27 EPS forecast I have JDO’s share price at $1.37, so let’s call in $1.40. Analyst forecasts or consensus has JDO at $1.55 per share. I am sure they do a lot more fancy calculations than me, but either way we are both in the same range. My thoughts at this stage are, I will wait until their FY26 numbers come out on the 18th August, to decide if I contribute more capital or not and then their HY27 numbers will be the real test. If they put out a good HY27 report. Then this is the point I will be expecting the market to re-rate their share price and where the $1.40-$1.55 valuation could come into play. At this point I will have to decide if I believe their growth story or sell their shares. If their share price reaches my valuation range beforehand, I will sell most of my holding and keep a small holding and go along for the ride.
Judo Capital Holdings ( ASX: JDO)
By Anton Crabbe July 6th 2026
I believe there is value in JDO’s share price currently. Their share price fell by more that 45% on the 25th of June. They started the day at $1.50 and closed at $0.90 making up some ground on the day. This fall was after they updated the market and cut their 2026 earnings forecast on the back of an increase in bad debts. Profit before tax is now expected to be between $163-$169m down from previous guidance of $180-$190m.
But this is the time you need to buy cyclical stocks like JDO, at or near the bottom of their cycle. For Australia to continue to be prosperous, then SME’s have to do well, and access to capital is key to this, and that’s what JDO do, lend money to SME’s. Business conditions are shot at the moment especially for SME’s but as the cycle begins to tick up again, JDO are in a positioned to benefit. I will do some numbers and further research on JDO and repot back soon!
P.S. I did by a parcel of JDO shares today 🙂
Disclaimer: Rational Share Investing With Ratios does not hold an AFSL and information on this site should not be considered financial advice, personal or general, and represents the views of the author.
Reference to specific securities (if any) is included for the purpose of illustration only and should not be construed as a recommendation to buy or sell the same. All securities mentioned herein may or may not form part of my holdings at a certain point in time, and the holdings may change over time.

