Buy Date: 29 July 2026 | Valuation $1.50
Stock Notes:
12th August 2026 | Share Price $0.52
VEE is expecting growth across all their businesses categories of defence, propulsion, gyrostabilisers and engineering. They raised $14m in FY25 to help with working capital in readiness for increase in defence and gyrostabilisers orders and expanded their propulsion capacity to accommodate for expected future demand.
VEE are also exploring entry into the US defence supply chain and see this potentially as a significant growth area. As I have noted in previous analysis VEE are a world class manufacturer of precision marine parts, products and systems via their in-house research and development. With this being their competitive advantage.
The next 2-3 years are looking positive for VEE and they have balance sheet strength and the technical capabilities to take advantage of the demand for their products and knowhow.
They are currently trading on a PE of 23.6 which is at the lower end of their PE range.
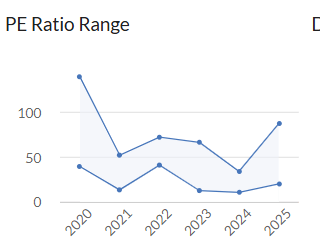
The market has gotten carried away with VEE before and I am not expecting this to happen again, but as demand keeps increasing and more orders start coming in. I will be expecting positive market updates and results to follow and I can see their PE ratio and share price heading higher.
I am waiting for their annual report due for release on 27th August 2026, before I do a more in-depth analysis and valuation. You can read previous articles here.
29th July 2026 | Share Price $0.51
I have bought back into VEE. After having a look at them again I believe there is value in their current share price of $0.51. I am looking at this investment from a minimum 2-4 year time frame. A few years ago the market got carried away and they where trading round $1.90 per share. Having bought them in 2023 at $0.57 per share and selling then at $1.40 in late 2024. As I was saving to buy a house and they were close to my $1.50 valuation and had come off their peak of $1.90. I still have a $1.50 valuation and believe the market has over sold them. Just like it over bought them in 2024.
I will provide more detail round my thinking shortly, but I will be waiting for their annual report to be released on 27th August before I do a full report on them and potentially buy more shares.
24th June 2024 | Share Price $1.67
VEE has provided forward guidance that they expect 2HFY24 revenue, earnings, and profits to be inline with 1HFY24 of $38m, $7m, and $3.5m respectively. This is inline with market consensus that revenue and profits for FY24 will be $74.8 and $6.4m respectively. As such, and VEE trading on a current PE of 55 and having a forward PE of 38. The market has priced in future earnings to VEE’s current share price and any pull-back to or below $1.50 is a price I’m happy to buy more shares at.
9th December 2023 | Share Price $0.89
Share price has run hard this year, up 57% on original investment. Will be waiting for further financial updates to see if they are on track to meet expectation. Think they are overvalued currently and future upside is being priced into their share price. I have long-term price target of $1.50. Possible buying opportunities on any share price correction or weakness from here.
VEEM Propelling Ahead
By Anton Crabbe 28th March 2024
VEEM (ASX:VEE) are a Perth based engineering firm specialising in marine propulsion and stabilisation systems for the global luxury motor yacht, fast ferry, commercial work boat, and defence industries.
Although the company is managed as a single business segment, VEE comprises the following sales categories Propulsion and Stabilisation, Defence, and Engineering. In my view and of VEE, their competitive advantage is their continued in-house R&D, allowing them to release and specialise in new and efficient technologies.
With their world class gyrostabilisers (gyros) and propeller products receiving ever increasing demand both at home and internationally, this is testament to their R&D abilities (more on this below). VEE are not an engineering services firm, but use their engineering prowess to design and manufacture world-class marine parts, products, and systems which they then market and sell.
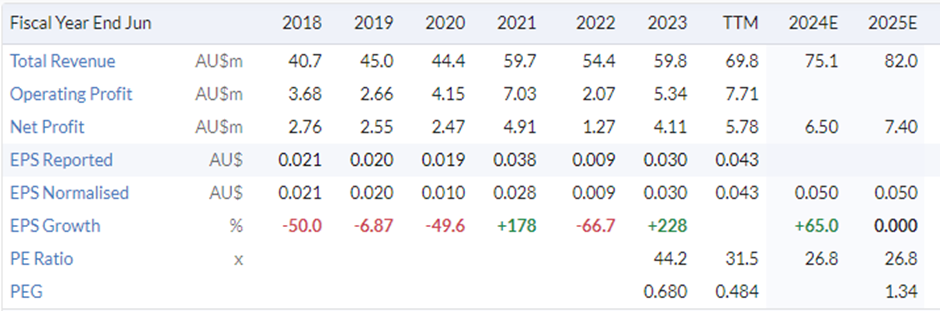
The last time I personally looked at VEE was in September 2023, where they had righted the ship after COVID impacted their ability to do business and profits had increased from a COVID induced low of $1.2m in FY22 to $4.1m in FY23. It is also a stock that Chris Batchelor had also discussed frequently.
As you would hope and expect with a near tripling of profits, VEE’s profitability and cash flow ratios improved substantially from FY22 to FY23 and have returned to pre-COVID levels. At this time VEE’s share price was 64c per share but on the back of signing an exclusive worldwide agreement to design, manufacture and sell Sharrow propellers in October 2023 (which according to VEE have a global addressable market of US$2.6bn, with the annual new build market of US$338m) and Strategic Marine bringing forward their order of 12 gyros (resulting in VEE expecting gyro revenue to double in FY24 to $10.0m) VEE’s share price shot up over the dollar mark and is currently around $1.50, at the time of writing.
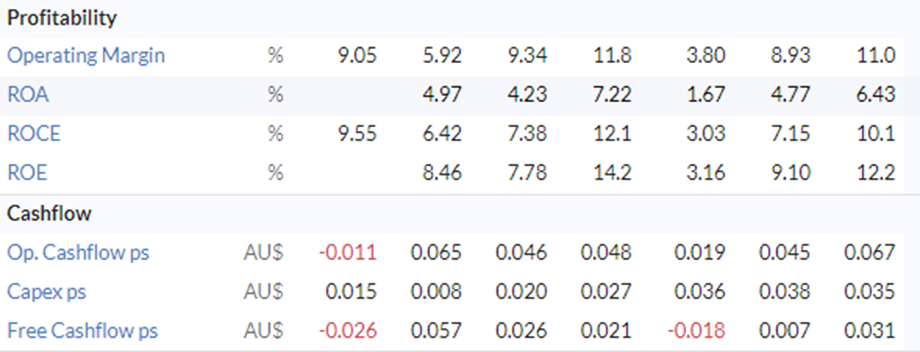
VEE have released their HY24 report, and it looks like the Momentum from FY23 is continuing. With revenue coming in at $37.5m up 37% for the half. Following suite, EBITDA and NPAT were up 65% and 92% to $6.9m and $3.5m for the half respectively. But for me, most importantly cashflow from operations was up 200% to $4.4m for the half. I purchased VEE at $0.57 in September 23. I have since taken profits on VEE and retain my original investment amount. I will continue to hold them long-term and look to buy on any share price weakness from here, more on this below.
StockRank:
On the back of VEE’s share price increasing some 170% since September 2023, you can see their value score has taken a hit. But on the back of VEE’s improved financial performance in FY23 and after releasing their HY24 report, VEE’s quality score has increased.
September 2023

March 2024

This is indicating the market does see VEE as a quality business, but at their current price they are expensive.
The main driver of their share price since September has been Momentum. A large part of VEE maintaining their momentum score was the forementioned Sorrow and Strategic Marine announcements. Furthermore, VEE was a new entrant to Stocks in the Shine Zone from this week’s Momentum Monday publication, written by Elio. Indicating further, that momentum has been a large driver of VEE’s share price of late. Me writing about it, also see’s it a topic of the Weekend Watchlist with Phil Muscatello and the Shares for Beginners Crew to be published on the weekend.
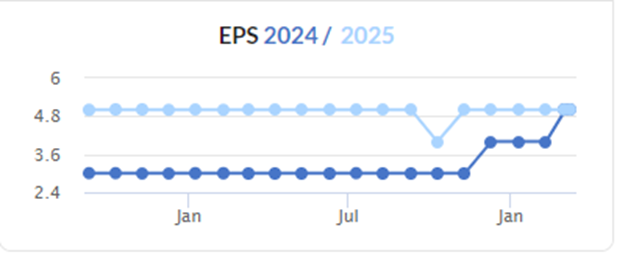
A quick look at VEE’s EPS for FY24-25 tells us this too. With EPS forecasts for FY24 increasing in late 2023. But FY25 remaining flat. For me this is indicating that VEE is fully priced, and their current share price has future earnings baked into it, and why I’m a buyer on any weakness in their share from here.
Financials:
As you would expect with a company that has a quality score of 91, VEE are in a good financial position and have been increasing sales, earnings and profits, post COVID.

Which is reflected in their F-score of 8. With the only blemish on their scorecard being they have been unbale to increase their ability to pay short-term debts. This is also reflected in their Z1-Score.


But with VEE’s liquidity and leverage ratios sitting at comfortable levels, their low M-score, and the substantial increase in operating cash flow for the half. I have no issues with their asset liquidity.
As we can see from VEE’s dividend cover, they have been very prudent paying dividends with a dividend cover above 3 or more, they have been retaining profits within the company. However, net debt has increased while average shares has remained flat. Highlighting, VEE has used debt to help fund their business. From here, it looks like VEE have clear seas ahead and sales, earnings and cash flow are improving. As such, I would like to see VEE maintain their prudent dividend policy, reduce debt levels, and if there are any surplus funds post capex and opex. VEE should return these to shareholders via dividends/special dividends. My preferred method of returning surplus capital is through share-buybacks but given the small number of shares on issue this is not really on option for VEE.

Liquidity and Ownership:
As with a lot of quality small cap businesses their shares can be closely held by top shareholders and VEE are no exception to this. With a market cap of $203.6m at the time of writing and only 131m share on issues, of which only 65.8m (48.5%) are classified as free float and can be traded. VEE’s shares are tightly held. With top shareholders accounting for 69% of this and directors John and Mark Miocevich holding 50% of VEE’s issued shares thorough their relevant interest in VEEM Corporation (family trust).

Over the last three months an average of 129k shares have traded on market per day. Which based on a share price of $1.50, is equivalent to a $193k parcel of shares. Indicating that share liquidity could be an issue for some DIY investor and the ability to build a large parcel of shares is limited.
Outlook:
For HY24 VEE saw $5.0m in gyro sales and had orders on hand for $9.2m, which they are expecting to deliver in FY24. On the back of building increased capacity in FY23. Propeller sales were up 41% to $16.5m for the half. With this contributing to a near doubling of NPAT for the half.
With this in mind, VEE gave the following forward guidance in their HY24 market release:
“Currently the outlook for the rest of FY24 is that the business will continue to deliver a similar revenue and profit outcome for the second half. Orders remain strong and we are confident that our worked hours and productivity will remain at the levels of the first half.”
Conclusion:
On the back of VEE’s share price more than doubling since September 2023, two significant business announcements, margins and cash flow returning to pre-covid levels. VEE have righted the ship post COVID and are steaming ahead. However, it does look like future earnings are baked into their share price and the small number of shares on issue with low share liquidity are risks investors need to consider before investing in VEE.
Smooth Seas Ahead
11th September 2023
Veem Ltd (ASX: VEE) are a Perth based engineering firm specialising in marine propulsion and stabilisation systems for the global luxury motor yacht, fast ferry, commercial work boat, and defence industries. Although the Group is managed as a single business segment, it can be broken down into the following sales categories: Propulsion and Stabilisation, which comprises, of the manufacture of new propellers, shaft lines, gyrostabilisers and marine ride control fins, Defence, and Engineering (non-defence). VEE’s main area of competitive advantage is their continued in-house R&D, allowing them to release and specialise in new and efficient technologies, with their world class gyrostabiliser and propeller products receiving ever increasing demand both at home and internationally, testament to their R&D abilities. VEE’s main area of focus is the development, marketing, sales and support of their products and services. COVID initially benefited VEE but as supply chains, availability of materials and labour were impacted by COVID, reducing VEE’s ability to do business and market their products, it hurt their bottom line.
FY22 was their worst year for some time with profits falling from $2.4m in FY20, $4.9m in FY21 to $1.27m. FY23 has seen profits return to previous levels coming in at $4.1m, indicating that things are on the improve and the worst is behind them. This has been reflected in their share price as it has gone from circa high of $1.40, low of 40c, to its current 63c, in this time.
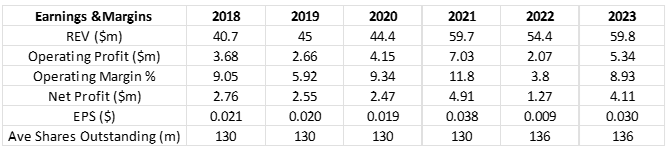
Things were heading in the right direction before COVID hit and impacted VEE’s ability to do business, and now after their FY23 numbers, it looks like things are on the improve again with revenue, profit, and margins increasing and getting back to their pre COVID levels, with this flowing through to EPS in FY23. Looking forward, operating profit and margins will be key as businesses get use to operating in a higher cost and inflationary environment post COVID, with businesses that keep a lid on costs and maintain or improve margins, set to do well. On the back of their FY23 numbers VEE look to be navigating the post COVID environment well and if this continues, they will perform solidly in the future.
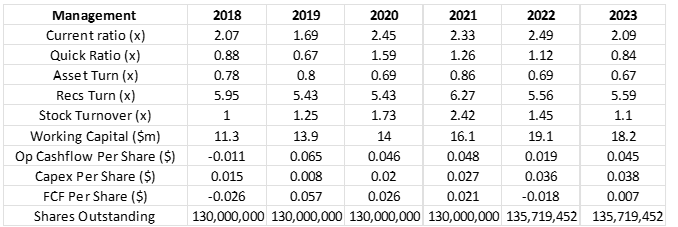
Management have performed well with the key liquidity ratios all remaining relatively consistent and at solid levels for an engineering company; Generally engineering firms have longer product cycles and therefor cash cycles than most companies. This is due to the longer time frames and higher costs associated with R&D, sales, manufacturing, and delivery/installation of their products before payment is received. We can see working capital has increased over the years as VEE have grown their business by increasing capacity. A large part of this has come in the last two years as capex per share levels have increased to 3.6c, significantly higher that previous years. In a market release on 24th August 2023 VEE’s MD Mark Miocevich noted:
“Importantly, VEEM invested $9.6m in capital and development assets during FY23 which will deliver improved returns for shareholders into the future through increased capacity, efficiency and product development. As always, VEEM’s R&D spend was significant at $2.8m for the year – another investment into the future of the company.”
This capex spend included three new propeller machining centres, associated equipment and tooling, with May and June FY23 each recording a new record for propeller sales as a result.
This capex has resulted in lower or negative FCF over the past 2-years and should start to improve as the intense capex spend reduces over the following years. As we are about to see in the next section management have elected to fund this growth mostly via debt as shares outstanding only increased by 5.7m over the last 6-years, a good sign management is on the same side as shareholders.
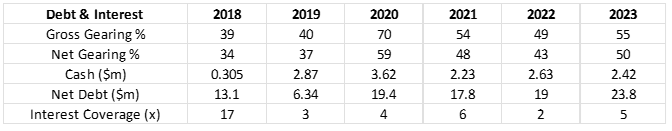
Debt levels sit at a comfortable level and have remained relatively consistent, except for FY20 which sore the onset of COVID, where companies looked to reinforce their balance sheet through increased debt and/or equity raisings. VEE has managed to reduce debt levels from their peak in FY20 significantly and return them to more sustainable levels, but for me there is still work to be done here and I would like to see management make an effort to reduce debt further or at the very least maintain current levels . VEE’s healthy interest coverage ratio of 5, along with, their sold liquidity ratios indicate that they will not have any issues maintaining current debt levels and meeting debt repayments.
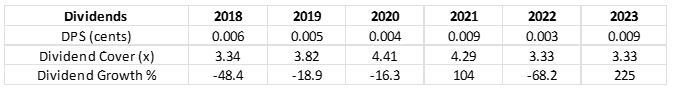
VEE’s management have been prudent with their dividend policy and have balanced the demand of shareholders and the requirements of the company by maintaining a dividend cover ratio of between 3 and 4. This has been reflected in dividend growth being inconsistent, but when profits have allowed VEE have increased their dividend payments. Ideally, as VEE’s performance becomes more consistent their dividend payments will become more stable and reliable.
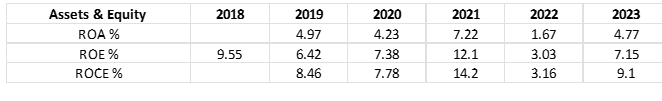
VEE’s performance here has been solid without being fantastic either and once again things were heading in the right direction before COVID. Given the high-cost low margin nature of their business if VEE can generate high single digit to low double-digit growth on assets, equity, and capital, while increasing revenue and maintain or increase margins, they will manage to generate health returns for shareholder. With this being a key minimum benchmark for continuing to hod the company, in my mind.
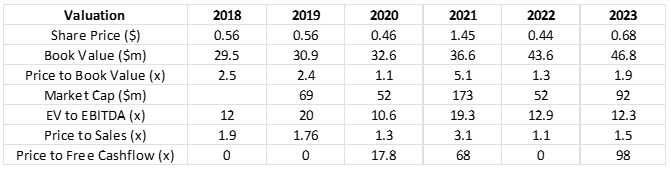
Depending on how you look at VEE they are either expensive or cheap. I bought them at 57c, and they are now 68c and up 20%. Basically, if you believe (like me) they are positioned to benefit from their R&D lead competitive advantage and demand for their products for some time to come, they are cheap or due to their small market position, high-cost low margin business, and low returns on assets, capital, and equity, they will struggle to create value for shareholders and are expensive.
Consensus forecast and estimates have revenue for FY24 and FY25 at $66m and $74m respectively with profits at $4.4m and $6.0m and EPS at 3cps and 5cps respectively. Highlighting, VEE are set to continue their growth path, with smooth seas and sailing set to continue. For anyone further interested in VEE and where they see themselves positioned in the market I would encourage them to read their outlook statement in their FY23 report: https://veem.com.au/investors-and-media/financial-reports/
Disclaimer: Rational Share Investing With Ratios does not hold an AFSL and information on this site should not be considered financial advice, personal or general, and represents the views of the author.
Reference to specific securities (if any) is included for the purpose of illustration only and should not be construed as a recommendation to buy or sell the same. All securities mentioned herein may or may not form part of my holdings at a certain point in time, and the holdings may change over time.

